


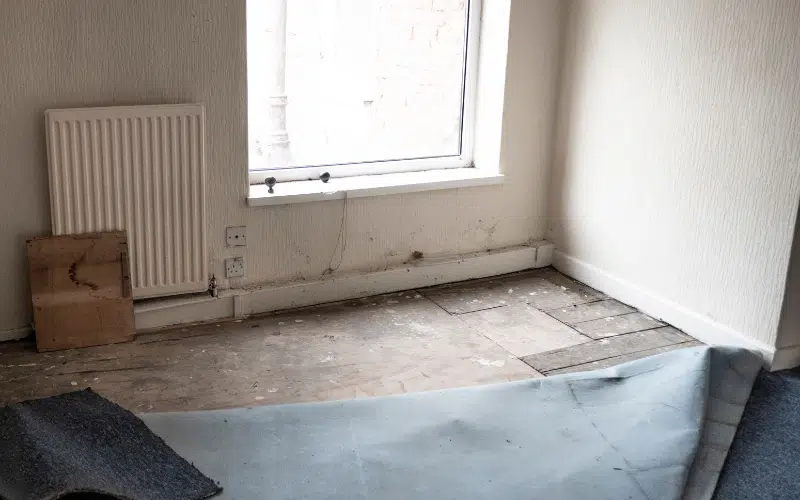
What Makes a House Habitable for a Mortgage (and What Makes It Unmortgageable?)
When applying for a mortgage, the lender needs to assess both you as the borrower and the property being offered as security.
The property normally needs to meet the lender’s minimum requirements for condition, marketability and suitability as mortgage security.
Not sure if a property is mortgageable?
If you’re unsure whether a property meets mortgage lenders’ requirements, it’s worth getting clarity before you commit.
At Kerr & Watson, we regularly help clients assess properties and understand their options, whether it’s a straightforward purchase or something more complex.
What Lenders Mean by Habitable
Mortgage lenders do not expect every property to be newly renovated, but the property normally needs to meet their minimum requirements as suitable mortgage security.
Requirements vary between lenders and the final decision can depend on the lender’s valuer. However, a mortgageable property will commonly need to be:
- Habitable
- Structurally sound
- Weatherproof
- Capable of being insured
- Readily saleable
- Provided with a working kitchen and bathroom
- Connected to essential services such as water and electricity
A property needing cosmetic work, a replacement kitchen or general modernisation is not automatically unmortgageable. The issue is usually whether the property can be safely occupied and provides acceptable security for the lender in its current condition.
If the property does not meet a lender’s minimum property requirements, it may not be acceptable for a standard residential mortgage until the required work has been completed.
What makes a property unmortgageable?
While a property doesn’t need to be perfect to get a mortgage, there are certain issues that can make it unacceptable to lenders.
In most cases, a property will be considered unmortgageable if it cannot be lived in safely or would be difficult for a lender to sell if repossessed.
- No functioning kitchen or bathroom
- Missing or unusable essential services such as water or electricity
- Serious structural defects or significant subsidence
- Major roof failure or water ingress
- Serious damp, rot or other defects affecting habitability
- Problems that prevent suitable buildings insurance being obtained
Depending on the severity of the problem and the lender’s criteria, the lender may request further reports, retain part or all of the mortgage advance pending works, or decline the property.
Common reasons a property may be declined for a mortgage
Some properties fall into a grey area, they may look fine at first glance but still raise concerns for lenders.
Common issues include:
- Properties without heating or with outdated systems
- Homes with significant damp or rot
- Non-standard construction (e.g. concrete, timber, or prefabricated homes)
- Properties in high-risk areas (e.g. flood zones or near mining)
- Flats above shops or near commercial premises
These issues do not automatically make a property unmortgageable, but they can reduce lender choice or result in the property being assessed under specific lender criteria.
Key habitability criteria lenders look for
The following areas are where surveyors and underwriters focus their attention. Understanding them helps you prepare, budget and plan your approach.
Kitchen and Bathroom That Work
A working kitchen and bathroom are common minimum requirements for standard mortgage lending.
The exact requirements vary between lenders and will depend on the lender’s valuer. However, a property where the kitchen or bathroom has been completely removed may not meet a lender’s habitability requirements.
A dated kitchen or bathroom is very different from a property where the essential facilities are missing or unusable. Cosmetic condition alone does not normally make a property unmortgageable.
Services and utilities
Serious defects with the electrical installation, heating, water supply or drainage may concern the lender’s valuer, particularly where they affect safety, habitability or marketability.
Structure, Cladding and Weatherproofing
Lenders need to see a structure that is sound and a building envelope that keeps out wind and water. This includes the main structural elements, the external walls and any cladding system in place. The property must demonstrate that it is stable, safe and properly weatherproofed.
Red flags include active subsidence, significant structural movement, failing lintels, rotten timbers, unsafe or non-compliant cladding, or a roof that allows water ingress. Roof coverings must be intact and appropriate for the design of the property, and external materials, including cladding, should not present fire risk or structural concerns.
A dilapidated roof, defective external walls, or problematic cladding can lead to a valuer recommending retention (pending further reports or remedial works) or, in more serious cases, an outright decline.
Roof types and lender comfort
A lender’s valuer will consider the condition, construction and marketability of the roof. An unusual roof covering does not automatically make a property unmortgageable, but significant defects, water ingress or difficulty obtaining suitable buildings insurance can cause problems.
Damp, mould and asbestos
Widespread damp and mould can indicate deeper issues such as defective gutters, poor ventilation, inadequate damp proofing or leaks. Where damp or mould appears significant, the valuer may recommend further investigation or remedial work before confirming whether the property is suitable security.
Asbestos does not automatically make a property unmortgageable. However, where suspected asbestos is damaged or considered a potential safety issue, a lender or valuer may require specialist advice or further investigation.
Building regulations and planning
Missing planning or building-regulation documentation can cause additional lender and solicitor enquiries, particularly where structural alterations have been carried out.
Depending on the circumstances, the lender’s solicitor may be satisfied with existing documentation, indemnity insurance or other evidence, while some cases may require further action before completion.
Examples include unapproved structural alterations, loft conversions without certification, or solar panel leases that impair the lender’s charge. Where paperwork is missing, indemnity insurance may be acceptable in some cases. In others, lenders prefer retrospective consent or evidence of compliance.
Gardens, boundaries and invasive plants
Japanese knotweed does not automatically make a property unmortgageable. The lender’s valuer may require a specialist report and, where treatment is recommended, evidence of an appropriate treatment plan or warranty.
The lender’s requirements will depend on the individual property and the extent of the problem.
Tenure and lease term
Leasehold properties also need to meet the lender’s lease requirements. A very short lease or unacceptable lease terms can make a property unsuitable for a particular lender even where the physical condition of the property is satisfactory.
Non standard construction and unusual features
Homes built using non-standard construction such as concrete panels or timber frames are not automatically unmortgageable, but lender criteria can vary significantly. The lender’s valuer may also require further information about the construction, condition, marketability or availability of buildings insurance.
Find out Your Options
Can You Get a Mortgage on an Uninhabitable Property?
If a property does not meet a standard mortgage lender’s minimum requirements, a normal residential mortgage may not be available in its current condition.
However, there may be alternatives depending on the property and the work required.
These can include:
- Bridging finance to purchase the property and fund or allow time for essential works
- Refurbishment finance where the property needs renovation before it becomes suitable for a standard mortgage
- A lender whose property criteria are suitable for the particular defect or construction type
Once the required work has been completed and the property becomes acceptable mortgage security, it may be possible to refinance onto a standard residential mortgage, subject to the borrower’s circumstances and the lender’s criteria at that time.
Short-term finance can be more expensive than a standard mortgage and requires a suitable repayment or refinance strategy, so the overall costs and exit should be understood before proceeding.
Example: Financing an Uninhabitable Property
A buyer agreed to purchase a property at a reduced price, but the kitchen had been completely removed and there was no functioning bathroom.
The lender’s valuation came back at £0, meaning a standard mortgage was not possible.
Instead, the buyer used short-term finance to complete the works and later refinanced onto a residential mortgage once the property met habitable standards.
Frequently Asked Questions About Habitable and Uninhabitable Properties
Do you need a kitchen to get a mortgage?
A working kitchen is a common minimum requirement for standard mortgage lending, although the exact criteria vary between lenders.
Can you get a mortgage without a bathroom?
A functioning bathroom is also commonly required for the property to meet a lender’s habitability criteria.
Can you get a mortgage on a renovation property?
Not always with a standard lender, but specialist finance options may be available.
What Does a £0 Valuation Mean?
A £0 or nil valuation does not necessarily mean the property has no value.
It usually means the valuer is not currently able to recommend the property as suitable mortgage security or provide a mortgage valuation in its present condition.
The lender may require further reports, information or remedial work before reconsidering the property. In some cases, the property may be declined.
Conclusion
For mortgage purposes, a property normally needs to meet the lender’s requirements for habitability, structural condition, marketability and buildings insurance.
A working kitchen and bathroom are common minimum requirements, while serious structural defects, significant water ingress, missing essential facilities or other major problems can result in further investigations, a retention or the property being declined.
Importantly, a property does not need to be modern or newly renovated to be mortgageable. Cosmetic work and general updating are very different from defects that prevent the property from providing acceptable security for the lender.
Not Sure If a Property Is Mortgageable?
If you are considering a property that needs work, it can be useful to check the likely mortgage position before you become committed to the purchase.
At Kerr & Watson, we can review the property and your circumstances and help identify mortgage or specialist finance options that may be suitable.














