


High Risk Occupations

Insurance for High-Risk Occupations
If you work in a job that’s considered high risk, you might have already heard that getting life insurance or income protection could be more complicated. But that doesn’t mean you’re out of options. Many insurers still offer comprehensive cover for people in riskier occupations, and with the right advice, you can secure a policy that suits your job, lifestyle and budget.
At Kerr & Watson, we understand the challenges faced by those in high-risk roles and help you find the right protection with no unnecessary hassle.
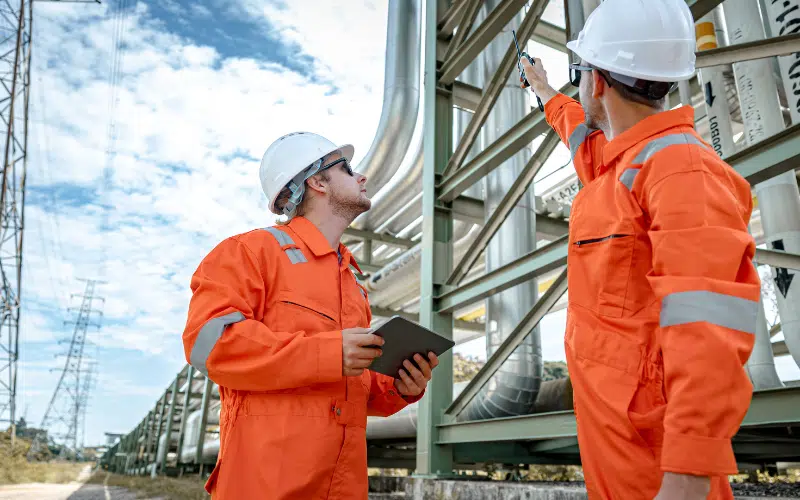
Why High-Risk Occupations Affect Your Protection Options
Working in a higher-risk occupation does not necessarily prevent you from getting protection, but your job and daily duties can affect the cover, insurer and terms available.
✓ People working in construction, roofing or at height
✓ Emergency services and military personnel
✓ Offshore, aviation and commercial diving workers
✓ People operating heavy machinery or specialist equipment
✓ Applicants previously offered exclusions or higher premiums
✓ Anyone wanting to compare insurers before applying
What Counts as a High Risk Occupation?
A high risk occupation is generally any job where there’s a higher-than-average chance of injury, illness or exposure to danger. Insurers use job titles and day-to-day duties to assess risk levels, which can affect your premium, exclusions, or even whether cover is offered.
Examples of high-risk jobs include:
- Construction workers and roofers
- Firefighters and police officers
- Offshore oil and gas workers
- Commercial divers
- Tree surgeons and arborists
- Pilots and aircrew
- Military personnel
- Stunt performers
- Professional athletes
- Roles involving heavy machinery or working at heights
Even if your job title doesn’t sound risky, certain tasks you perform regularly might still place you in a higher risk category. That’s why insurers look closely at your exact responsibilities, not just your job title.
How Does a High Risk Job Affect Life Insurance?
Working in a hazardous occupation doesn’t mean you’ll be refused life cover. However, it may affect the terms of your policy. Here’s how:
- Higher premiums: Because the insurer sees more risk of a claim, you may pay more than someone in a lower-risk profession.
- Exclusions: Some insurers may offer you cover but exclude death or injury from specific activities linked to your job.
- Additional questions: You may be asked more in-depth questions about your duties, work environment, and safety training.
- Delayed underwriting: If your role is especially complex or involves overseas travel, the process might take longer.
The good news is that many insurers are happy to cover people in high-risk jobs, you just need to apply with the right provider.
At Kerr & Watson, we know which insurers may take a more flexible approach to risk, and we tailor your application accordingly.
What About Income Protection?
Income protection is very important, especially if you’re in a high-risk occupation, particularly if your job relies on physical ability.
This type of cover pays a monthly income if you’re unable to work due to illness or injury and it’s a crucial safety net if your work puts your body on the line.
Here’s what you need to know:
- Your job will influence the premium: Manual roles often come with higher premiums than desk-based jobs.
- Deferred periods may vary: You can choose how long you wait before a claim pays out, usually 4 to 52 weeks. Some risky occupations may be limited to longer deferred periods.
- Benefit limits may apply: Insurers often cap the percentage of your income that can be insured, usually around 50-70%.
Again, not all providers treat risk the same way. Some specialise in income protection for tradespeople, offshore workers, or people who use dangerous equipment/
Common Mistakes to Avoid
If you’re in a high-risk job, there are a few pitfalls to watch out for when applying for protection:
- Using a generic comparison site: These don’t always consider the details of your job or necessarily recommend insurers who specialise in covering high-risk roles.
- Being vague on your application: Omitting key duties like working at heights or using hazardous materials can lead to a declined claim later on.
- Assuming you can’t get cover: Many people wrongly think they’re uninsurable due to their job, when in fact they may have just not applied in the right place.
How We Help at Kerr & Watson
We work with clients from a wide range of professions, including those in jobs considered high-risk by insurers.
We help people working in higher-risk occupations, including scaffolders, offshore workers and emergency services personnel, find insurance cover suited to their jobs and individual circumstances.
Here’s what we offer:
- Guidance on which providers are most suited to your occupation
- Support with presenting your duties accurately to underwriters
- Access to specialist insurers not available on standard comparison sites
- Help with balancing cover levels, deferred periods and costs
- Ongoing support to adjust your cover as your role evolves
Our approach is about understanding your role and recommending protection that matches your risks, without overselling or making things more complicated than they need to be.
Conclusion
Working in a higher-risk occupation doesn’t necessarily mean you can’t get life insurance or income protection. The key is finding an insurer that understands the nature of your work and can offer suitable cover at a reasonable cost.
At Kerr & Watson, we help people in physically demanding and higher-risk jobs understand their insurance options. Get in touch with our team to discuss your circumstances and find out what cover may be available.
Your Insurance In 3 Easy Steps…
Conversation
Send us an enquiry to arrange a call to speak to an adviser about your needs and situation. Alternatively give us a call on 01252 224620 or email us on info@kerrandwatson.co.uk.

Research
We will take the information gained on the call and carry out some research before sending you a bespoke recommendation.
Application
Once we have the relevant information, we will complete your insurance application and update you throughout the process.
Featured In





Testimonials


Awards & Recognition




Contact Us
Free initial conversation. No obligation.
We aim to respond within a few working hours.
By submitting, you agree to be contacted about your enquiry. See our Privacy Policy.