Self-Employed Mortgages

We understand how you work. Let us find a lender that will too.
Lenders assess the income of self-employed people in many different ways. Some will take an average of salary and dividends over the last two years whereas others may be more interested in the latest year and the overall profits of the business.
Kerr & Watson will spend time understanding your business and income to then recommend the lender that is the most suitable to meet your needs. We can also work alongside your accountant to gain a full picture.
How We Help with Self-Employed Mortgages
At Kerr & Watson, we help self-employed customers find suitable mortgages by understanding how their businesses operate and how different lenders assess their income.
✓ Sole traders and partnerships – Comparing lenders that assess net profit and varying annual earnings.
✓ Limited company directors – Exploring lenders that consider salary, dividends and company profits.
✓ Contractors and freelancers – Identifying lenders that assess contract income, including those using day rates.
✓ Recently self-employed – Exploring mortgage options for customers with one year’s accounts or a shorter trading history.
How Do Mortgage Lenders Assess Self-Employed Income?
Mortgage lenders calculate self-employed income differently, which can significantly affect how much you can borrow.
For example, some lenders assess company directors using salary and dividends, while others may consider their share of company profits. Sole traders are generally assessed using net profit, while some contractors can qualify based on their day rate.
We compare these different approaches to identify lenders whose affordability assessments best reflect your circumstances.
Can You Get a Mortgage with One Year’s Accounts?
Many mortgage lenders prefer at least two years of self-employed income history, but some may consider applications with just one year’s accounts.
Lenders also take different approaches to fluctuating income. Some average earnings over two years, while others may consider the latest year’s figures, depending on the circumstances.
We review your trading history, accounts and supporting documents to identify lenders whose criteria may suit your situation.
How Much Can You Borrow If You’re Self-Employed?
The amount you can borrow depends on how a lender calculates your income, as well as your financial commitments, credit history and mortgage term.
Some lenders average your earnings over two years, while others may use your latest year’s income or take a different approach to company profits. This means two lenders could offer considerably different borrowing amounts based on the same accounts.
We compare lender affordability assessments to establish how much you may be able to borrow before applying for a mortgage.
Mortgage Calculator
Calculate your borrowing potential with our affordability calculator.
Identify what your monthly repayments would be with our repayment calculator.
Confirm your Stamp Duty costs with our Stamp Duty calculator.
How to Get your Tax Calculations and Tax Year Overviews?
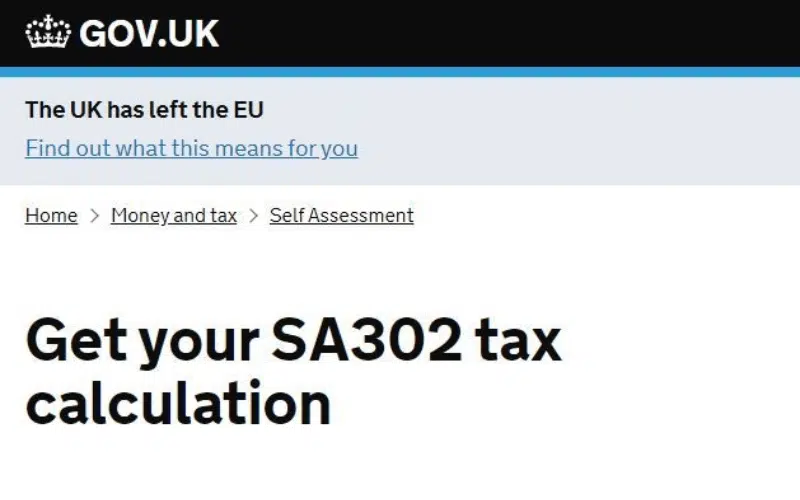
If you are self-employed or a limited company director, mortgage lenders nearly always require you to provide your SA302 (Tax Calculations) & Tax Year overviews to support and evidence the income you have earned and declared for your employed, self-employed, dividend and property related remuneration.
Find out how you can get your Tax Calculations and Tax Year Overviews.
Your Mortgage In 3 Easy Steps…
Conversation
Send us an enquiry to arrange a call to speak to a mortgage adviser about your circumstances, borrowing requirements and property plans.
Alternatively give us a call on 01252 224620 or email us on info@kerrandwatson.co.uk.
Research
We will use the information you’ve provided to research suitable mortgage options across the market and explain our recommendation to you.
If you need an Agreement in Principle, we can also arrange this as part of the process.
Application
Once you’re ready to proceed, we will submit the full mortgage application and supporting documents to the lender.
We will liaise with the lender and its underwriters, respond to any additional requirements and keep you updated until the mortgage offer is issued and through to completion.


Testimonials


Featured In






Awards & Recognition







Contact Us
Free initial conversation. No obligation.
Not ready to apply yet? That’s fine — we can start with a quick conversation about your options.
We aim to respond within a few hours during working days.
By submitting this form you agree that Kerr & Watson may contact you regarding your enquiry.
Your information will be handled in accordance with our Privacy Policy.