
Inflation History
UK Inflation History
Keep up to date with the history of UK inflation and how the Consumer Prices Index (CPI) has changed over time.
We regularly update this page using information from the Office for National Statistics (ONS) to provide a straightforward record of UK inflation, including monthly CPI figures, changes over time and how inflation can affect Bank Rate, mortgage rates and the wider economy.
Current UK Inflation Rate
The current UK Consumer Prices Index (CPI) inflation rate is 3.1%, based on the latest figures for August 2026.
This was up from 2.9% in July 2026. The Office for National Statistics reported that transport costs, particularly motor fuels, made the largest upward contribution to the change in the annual inflation rate.
The Bank of England’s inflation target is 2%, and CPI is the measure it uses when assessing whether inflation is above or below that target.
The next UK inflation figures are due to be published on 21 October 2026.
For our latest commentary on Bank Rate, mortgage rates, inflation and the wider housing market, visit our Mortgage & Housing Market Update.
What Is Inflation?
Inflation measures how quickly the prices of goods and services are changing over time.
In the UK, one of the main measures is the Consumer Prices Index (CPI). The Office for National Statistics tracks the prices of a large basket of goods and services and uses this information to calculate how prices have changed compared with a year earlier.
For example, if CPI inflation is 3%, this broadly means that the prices measured by the index are around 3% higher than they were a year earlier.
Inflation matters because it affects household spending, savings, wages, business costs and the wider economy. It is also one of the most important factors considered by the Bank of England when setting Bank Rate.
UK Inflation History
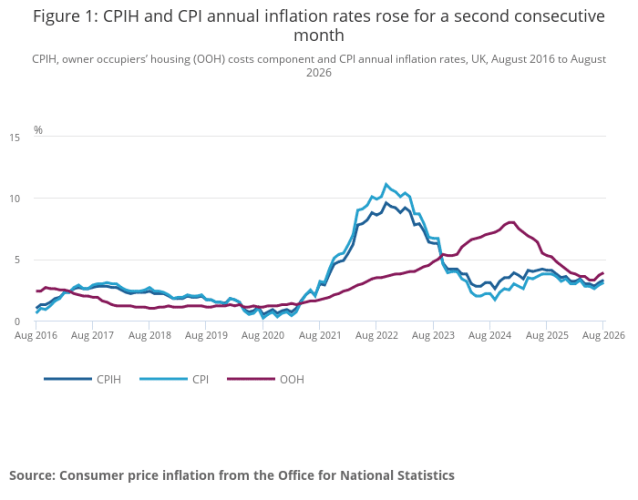
The chart below shows how Inflation has changed over time.
UK Inflation in 2026
| Month | CPI Inflation | Change in Annual CPI Rate |
|---|---|---|
| August 2026 | 3.1% | +0.2 percentage points |
| July 2026 | 2.9% | +0.3 percentage points |
| June 2026 | 2.6% | −0.2 percentage points |
| May 2026 | 2.8% | No change |
| April 2026 | 2.8% | −0.5 percentage points |
| March 2026 | 3.3% | +0.3 percentage points |
| February 2026 | 3.0% | No change |
| January 2026 | 3.0% | −0.4 percentage points |
For more context on how inflation influenced interest rate expectations and the mortgage market during 2026, explore our monthly market updates:
- September 2026 Mortgage Market Update
- July 2026 Mortgage Market Update
- June 2026 Mortgage Market Update
UK Inflation in 2025
| Month | CPI Inflation | Change in Annual CPI Rate |
|---|---|---|
| December 2025 | 3.4% | +0.2 percentage points |
| November 2025 | 3.2% | −0.4 percentage points |
| October 2025 | 3.6% | −0.2 percentage points |
| September 2025 | 3.8% | No change |
| August 2025 | 3.8% | No change |
| July 2025 | 3.8% | +0.2 percentage points |
| June 2025 | 3.6% | +0.2 percentage points |
| May 2025 | 3.4% | −0.1 percentage points |
| April 2025 | 3.5% | +0.9 percentage points |
| March 2025 | 2.6% | −0.2 percentage points |
| February 2025 | 2.8% | −0.2 percentage points |
| January 2025 | 3.0% | +0.5 percentage points |
Source: Office for National Statistics: Inflation and price indices
Find out Your Options
How Has UK Inflation Changed Over Time?
UK inflation has moved through periods of both relatively low and unusually high price growth.
Following the financial crisis, inflation fluctuated but generally remained much closer to the Bank of England’s 2% target than during the sharp increase seen in the early 2020s.
Inflation then fell significantly during the Covid-19 pandemic before rising rapidly as the economy reopened. Global supply disruption, higher energy and food prices and other cost pressures contributed to a substantial increase in inflation.
UK CPI inflation reached particularly high levels during 2022 before beginning to fall as energy-price pressures eased, supply conditions improved and higher interest rates reduced demand.
Inflation has since moved closer to the Bank of England’s target, although monthly figures can still rise or fall depending on movements in areas such as energy, food, transport and services.
What Is the Bank of England Inflation Target?
The UK Government sets the Bank of England an inflation target of 2%, measured using CPI.
The target does not mean inflation must remain at exactly 2% every month. Inflation can move above or below the target as economic conditions change.
The Bank of England aims to return inflation sustainably towards 2% over time when deciding the appropriate level of Bank Rate.
Why Does Inflation Rise and Fall?
Inflation can change for many reasons. Common influences include:
- energy prices
- food prices
- wages
- transport costs
- supply shortages
- exchange rates
- consumer demand
- taxes and government policy
- international economic events
Inflation can also vary between different parts of the economy. For example, goods inflation may be falling while services inflation remains relatively high.
CPI vs CPIH vs RPI
| CPI | CPIH | RPI | |
|---|---|---|---|
| What is it? | Consumer Prices Index | CPI including owner-occupiers’ housing costs | Retail Prices Index |
| Used for Bank of England target? | Yes | No | No |
| Includes owner-occupier housing costs? | No | Yes | Uses a different methodology |
| Published by | ONS | ONS | ONS |
| Best measure for this page? | Yes | Useful additional measure | Mainly historical/contractual uses |
How Does Inflation Affect Bank Rate?
Inflation is one of the most important factors considered by the Bank of England when setting Bank Rate.
When inflation is persistently above the 2% target, higher interest rates can help reduce demand by making borrowing more expensive and encouraging saving.
When inflationary pressure falls and economic conditions allow, the Bank of England may have more scope to reduce Bank Rate.
However, there is no automatic formula linking a particular inflation figure to a Bank Rate decision. The Monetary Policy Committee considers a wide range of economic information.
How Does Inflation Affect Mortgage Rates?
Inflation can influence mortgage rates indirectly through expectations for Bank Rate and financial markets.
If inflation is higher than expected, markets may anticipate that Bank Rate will need to stay higher for longer. This can push up swap rates and put upward pressure on fixed mortgage pricing.
If inflation falls faster than expected, markets may reduce their expectations for future interest rates. Swap rates may then fall, potentially giving lenders more scope to reduce fixed mortgage rates.
Mortgage rates are therefore influenced by more than the headline inflation figure alone.
Inflation, Bank Rate, Swap Rates and Mortgage Rates
| Inflation | Bank Rate | Swap Rates | Mortgage Rates | |
|---|---|---|---|---|
| What is it? | Measure of price changes | Official policy interest rate | Market expectations for future rates | Rates charged on mortgage products |
| Who determines it? | Measured by ONS | Bank of England MPC | Financial markets | Mortgage lenders |
| Can it change monthly/daily? | Published monthly | At MPC decisions | Can move daily | Can change at any time |
| Can it influence fixed mortgages? | Indirectly | Indirectly | Often significantly | Final rate offered to borrower |
Inflation, Bank Rate, swap rates and mortgage rates are connected, but they do not move in exactly the same way or at the same time.
Does Falling Inflation Mean Mortgage Rates Will Fall?
Not necessarily.
Lower inflation can support expectations for lower interest rates, but mortgage rates are also affected by swap rates, market expectations, lender funding costs and competition.
Financial markets often move before official economic decisions are made. This means fixed mortgage rates can fall before Bank Rate is reduced, or rise even when the latest inflation figure has improved.
Looking for Mortgage Advice?
Inflation, Bank Rate and swap rates can all influence mortgage pricing, but the effect on an individual borrower depends on their circumstances and the type of mortgage they require.
If your current mortgage deal is approaching its end, or you would like to understand the options currently available, Kerr & Watson can compare suitable mortgages from across the market and provide advice based on your circumstances. Speak to an Adviser
Why Kerr & Watson?
Understanding
We take the time to understand your situation so that we can search for the most suitable mortgage and insurance for you. Any recommendation made is completely bespoke to your circumstances.
Experience
Mortgage and insurance advice is our speciality. We have decades of combined experience giving us the knowledge to overcome challenges and find the appropriate solution for your needs.
Communication
We work around your schedule to arrange a mortgage or insurance policy that suits your needs. You’ll be kept updated throughout the entire process with clear communication so you’ll always know what’s going on.
Featured In






Testimonials


Awards & Recognition







Contact Us
Free initial conversation. No obligation.
Not ready to apply yet? That’s fine — we can start with a quick conversation about your options.
We aim to respond within a few hours during working days.
By submitting this form you agree that Kerr & Watson may contact you regarding your enquiry.
Your information will be handled in accordance with our Privacy Policy.