Commercial Mortgage for B8 Properties: Warehouses, Storage Units and Distribution Centres
If you are looking at a warehouse, storage unit, or distribution centre, you are likely dealing with Use Class B8. You might be buying for your own business. You might be investing and letting the unit to a tenant. Either way, you want clarity.
You want to know what lenders accept. You want to understand deposit expectations. You also need to avoid planning surprises that can delay a purchase.
What is a B8 property?
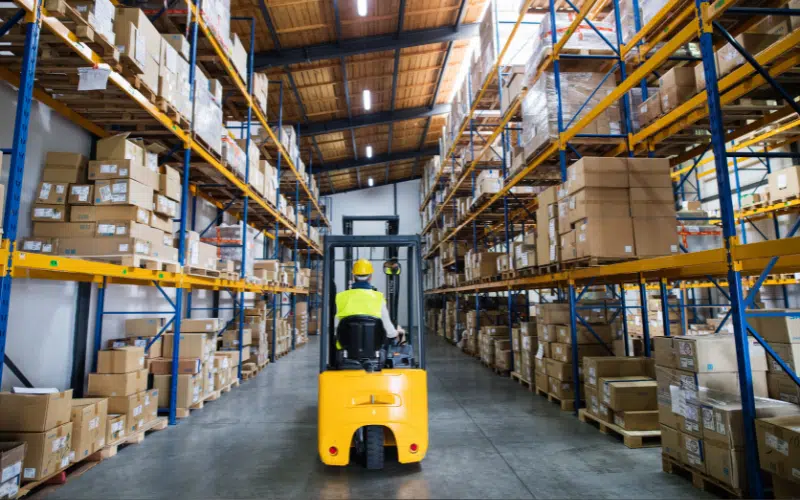
B8 refers to storage and distribution. In simple terms, B8 covers premises where the main activity is storing goods, moving goods, or preparing goods for dispatch.
You will often see B8 used for:
- Warehouses and logistics units
- Distribution hubs and fulfilment centres
- Self storage sites and document storage
- Cold storage and racked storage facilities
- Container yards and open storage compounds
- Builders yards and storage depots
- Vehicle depots where storage is the main activity
A useful rule of thumb is this. If you store and move goods, you are closer to B8. If you manufacture, you are more likely in B2. If you sell to the public as your main activity, you are likely in a different class.
Many sites have ancillary space, such as offices or a small trade counter. This can still sit within B8 when it supports the main storage use.
Why Use Class B8 matters for your mortgage
Lenders do not just lend on bricks and mortar. They lend on risk.
Use class shapes that risk because it affects demand, rental appeal, valuation, and resale prospects. B8 has become a core part of supply chains, which can support lender appetite. Yet B8 can also trigger concerns, especially where there is heavy traffic, late operating hours, or sensitive neighbours.
When you present a B8 mortgage case well, you make it easier for a lender to say yes. You also reduce the chance of delays after valuation.
What is a commercial mortgage on a B8 property?
A commercial mortgage is a loan secured against a property that is not your main home. When that property is a B8 warehouse or distribution unit, the lender treats it as commercial property lending.
You can use a B8 commercial mortgage to:
- Buy a warehouse for your own operations
- Buy a unit to rent to another business
- Refinance an existing loan and improve terms
- Release capital for growth, stock, or expansion
- Purchase a site with a clear plan for use and income
Commercial mortgages tend to be assessed on affordability from business cash flow or rental income, rather than only personal income.
Find out Your Options
Owner occupier vs investment mortgages for B8
Your route depends on how you will use the property.
Owner occupier B8 mortgage
You buy the unit and trade from it. Lenders focus on your business performance and how the premises supports your operations.
You may like this route if you want to control your premises and reduce exposure to rent increases. You also build equity as you repay the mortgage.
B8 commercial investment mortgage
You buy the property and let it to a tenant. Lenders focus on the lease, the rent, and the tenant strength.
A strong lease can improve lender appetite. A weak lease can narrow options and reduce loan to value.
Typical loan to value for B8 commercial mortgages
Loan to value, often called LTV, is the percentage of the property value the lender will fund.
Typical ranges often look like this:
- Owner occupier B8 mortgages can reach up to around 75 percent, and sometimes higher for strong cases.
- Investment B8 mortgages often sit up to around 70 to 75 percent, depending on the tenant and lease.
This means you may need a deposit in the 25 to 40 percent range, depending on the deal.
If you want to borrow more, you may be able to use additional security. This can include another property, subject to lender approval. It can also include cash reserves and a strong affordability profile.
Interest rates and terms for B8 mortgages
Commercial mortgage pricing is usually bespoke. Lenders price based on risk, security, and affordability.
Rates can be fixed or variable. Variable rates often track an underlying benchmark plus a margin. Your margin depends on the lender’s view of your case.
Loan terms often range from 15 to 25 years. Some lenders can consider longer terms in the right scenario.
You may choose:
- Capital repayment, where you reduce the balance monthly.
- Interest only, where you pay interest and repay later, with a clear exit plan.
The right structure depends on your cash flow goals and your long term plan.
What lenders look for on a B8 commercial mortgage
Lenders tend to assess three areas.
Your financial strength
If you occupy the unit, lenders often ask for:
- Two to three years accounts where available
- Recent bank statements
- Management figures if needed
- A clear view of assets and liabilities
- A short business plan and projections
If you invest, lenders look at rental income and coverage. They also look at your experience and portfolio, if you have one.
The property and valuation
The lender will instruct a valuation. The valuer considers location, condition, access, and market demand. They also look at suitability for storage use.
B8 properties often need strong access for HGVs and vans. They also benefit from secure yards, loading doors, and appropriate power.
If the unit is older, you may need to consider energy efficiency and condition. These factors can influence lender comfort and tenant demand.
The planning position
You should confirm the planning use class matches your intention. If you plan to change the use, you must understand the planning route.
Some changes can fall under permitted development in limited cases. Many changes require a full planning application. Local authority policies and Article 4 directions can also restrict flexibility.
A lender wants clarity. Uncertainty can slow underwriting or trigger extra conditions.
Planning considerations you should not ignore
B8 sites often bring practical impacts that planning officers scrutinise. These same impacts can affect lender confidence too.
Expect questions around:
- Traffic and access, including HGV movements
- Loading bays and yard design
- Noise from reversing alarms and late operations
- Light spill from security lighting
- Flood risk for low lying sites
- Operating hours and neighbour sensitivity
If you are buying a site with conditions attached, you should read them early. Conditions can restrict hours, noise controls, or use of external areas. A restriction can affect your business plan and rental demand.
Costs and fees to budget for
Commercial mortgages come with costs beyond the deposit. You should plan for:
- Valuation fees
- Legal fees for your solicitor and the lender’s solicitor
- Arrangement fees charged by the lender
- Broker fees where applicable
- Survey and condition reports if required
These costs vary by lender and property value. A clear budget avoids stress close to completion.
Common questions people ask about B8 commercial mortgages
Can you get a commercial mortgage on a leasehold B8 unit?
Yes, many lenders accept leasehold. They usually want a long unexpired term. In practice, you often need several decades left.
Can you change from B2 to B8 without full planning?
Some routes allow limited changes subject to conditions, such as size limits and local rules. Always check with the local planning authority early.
Can you convert a B8 warehouse into homes?
This is more difficult than it used to be. Many projects now need a full planning application rather than an automatic route. Prior approval and local policy can also shape outcomes.
Do lenders prefer certain types of B8 tenants?
Many lenders like long leases with stable tenants. They also like clear repairing obligations and predictable rent reviews. Strong tenant covenants can improve terms.
What deposit should you expect for a B8 mortgage?
Many deals sit around 25 to 40 percent deposit, depending on the case. Strong affordability and security can improve the outcome.
Conclusion
A B8 property can be a strong base for your business or a solid commercial investment.
You can secure a commercial mortgage on a warehouse, storage unit, or distribution centre when you present the required information and choose the right lender.
If you are buying or refinancing a B8 property, speak to contact Kerr & Watson today.