
Payslips and Mortgage Applications: What Lenders Want to See
Mortgage lenders use your payslips to check your income, employment and whether the earnings shown on your mortgage application can be evidenced.
For straightforward employed income, lenders will commonly ask for between one and three recent monthly payslips, although the exact requirement varies. If you are paid weekly or fortnightly, receive variable income, or have recently changed jobs, you may need to provide additional evidence.
Lenders may check your basic salary, overtime, bonuses, commission, deductions and whether the income shown on your payslips matches the salary being paid into your bank account. The way this income is assessed can vary considerably between lenders.
How many payslips do you need for a mortgage?
There is no single number of payslips required by every mortgage lender. If you are employed and receive a regular monthly salary, lenders will commonly ask for between one and three of your most recent payslips.
The amount of evidence required can depend on how often you are paid and the type of income being used. If you are paid weekly, fortnightly or every four weeks, the lender may ask for more payslips so they can review a similar period of income.
You may also need to provide more evidence if your income includes overtime, commission, bonuses, shift allowances or other variable payments.
How many months of payslips do mortgage lenders need?
For a straightforward monthly basic salary, one to three months of payslips is common, depending on the lender.
If some of your income changes from month to month, a lender may want to see a longer history before deciding how much of that income it is prepared to use. The evidence required can also depend on how frequently additional income is paid. For example, annual or quarterly bonuses may need to be evidenced over a longer period than monthly overtime.
If you are paid weekly or fortnightly, you may therefore be asked for a greater number of payslips even though the period of income being assessed is broadly similar.
Can you get a mortgage with only one payslip?
Yes, potentially. Some mortgage lenders can consider an application using your latest payslip where you receive a regular employed salary and meet their other criteria.
This can also be possible if you have recently started a new job. Depending on the lender and your circumstances, you may be asked to provide your employment contract or other evidence confirming your salary, start date and employment terms.
You do not necessarily need to wait until you have three months of payslips before applying for a mortgage. This is an area where lender criteria vary, so choosing a lender that is comfortable with your employment circumstances can be important.
Do mortgage lenders need payslips for overtime, bonuses and commission?
If you want overtime, bonuses or commission included when calculating how much you can borrow, the lender will normally want evidence that the income has been received.
Different lenders assess additional income in different ways. Some may look at the most recent few months, while others require a longer track record. The lender may average the income received and may use all or only part of it when calculating affordability.
How frequently the additional income is paid can also make a difference. Regular monthly overtime may be assessed differently from a quarterly or annual bonus.
This means two lenders can calculate your usable income differently even when looking at exactly the same payslips.
Not sure whether your income will be accepted by lenders?
Mortgage lenders do not all calculate income in the same way. This can be particularly important if you have recently changed jobs or receive overtime, bonuses, commission, shift allowances or income from more than one job.
At Kerr & Watson, we can review how your income is structured and identify lenders whose criteria are suitable for your circumstances.
Why do mortgage lenders ask for payslips?
Lenders use payslips to verify your income and help assess whether the mortgage you are applying for is affordable. They may also use them to establish how much of your basic and additional income they are prepared to include in their affordability calculation.
What do lenders check on payslips?
Lenders usually review:
- Your basic salary
- Overtime, bonuses, and commission
- Employment status and employer details
- Tax and National Insurance deductions
- Student loan or pension deductions
- Consistency of income
- Whether your income matches your bank statements
They use this information to assess affordability and the stability of your employment.
The way each item is treated can differ between lenders. This is particularly relevant if a large part of your total income comes from overtime, commission, bonuses, allowances or a second job.
What information do mortgage lenders look for on a payslip?
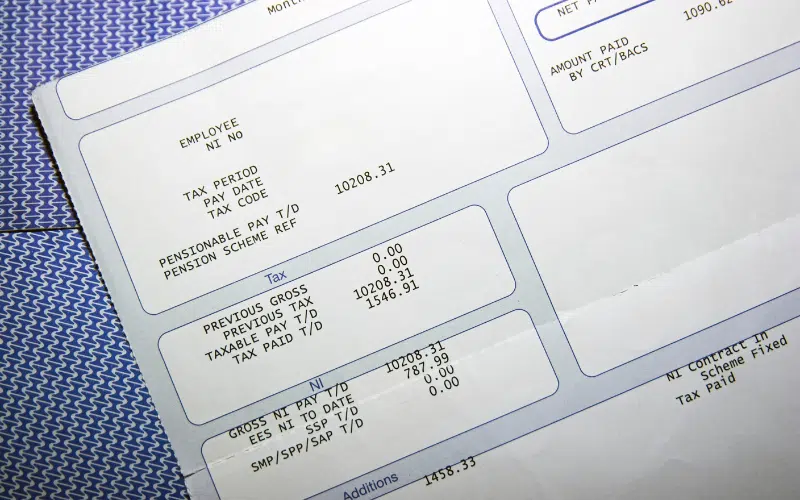
For a lender to consider your payslips valid, they usually expect to see:
- Your full name (matching your bank statements and ID)
- The name of your employer
- The payment date and period covered
- Your gross pay (earnings before deductions)
- Your net pay (take-home pay)
- National Insurance and tax deductions
- Any additional income like bonuses or overtime
This data helps lenders build a picture of your income and overall affordability.
Can you get a mortgage while on probation?
Yes — some lenders will consider applicants who are still within their probation period.
This depends on:
- Your employment history
- The industry you work in
- Whether your role is permanent
- How long is left on your probation period
Some lenders may require you to pass probation first, while others are more flexible.
If you have recently started a new job, you can also read our guide to getting a mortgage when you have recently changed jobs or speak to us about which lenders can consider your circumstances.
What deductions do lenders consider?
It’s not just what you earn that matters, but also what you owe. Lenders will examine your deductions to determine how much disposable income you have. Key deductions include:
- Student loan repayments
- Pension contributions
- Salary sacrifice schemes (like cycle to work or childcare vouchers)
- Child maintenance payments
- Car finance or salary sacrifice car schemes
These deductions reduce your take-home pay, and some lenders factor this into your affordability assessment.
Others may consider your gross income, particularly if deductions are voluntary. That’s why getting personalised advice is worthwhile.
The impact of a deduction depends on what it relates to and the lender’s affordability calculation. For example, student loan repayments can reduce the income available for mortgage affordability, while voluntary pension or salary sacrifice arrangements may be treated differently between lenders.
Find out Your Options
What if your payslip does not match your bank statement?
Mortgage lenders may compare the net salary shown on your payslip with the salary payments appearing on your bank statements.
If the figures do not appear to match, it does not automatically mean there is a problem. There may be a straightforward explanation, such as salary being paid into a different account, a bonus being paid separately, salary sacrifice deductions, payroll adjustments or a difference between the payslip date and the date the money reaches your account.
The lender may ask for an explanation or additional evidence if there is a difference it cannot easily understand.
Common mistakes to avoid
Understanding your payslip can be tricky, especially if your income varies. Here are some pitfalls that could hold up your mortgage application:
- Submitting outdated payslips
- Providing cropped or incomplete documents
- Not providing enough evidence for overtime, bonuses or other additional income you want the lender to use
- Not updating your employer with your correct address, resulting in outdated addresses showing on your payslips.
- Providing screenshots instead of full PDF payslips
Can you get a mortgage without payslips?
Yes, in some circumstances. Not having conventional payslips does not automatically prevent you from getting a mortgage. The evidence needed will depend on why you do not have payslips and how your income is earned.
you have only recently started a employed contract, some lenders may be able to use an employment contract alongside any payslip you already have.
If you are self-employed, payslips would not normally be expected unless you also receive PAYE income. Instead the documents required for a self -employed person would be, Tax Calculations, Tax Year Overviews and, depending on the lender and business structure, business bank statements.
Depending on your situation, you may be asked for:
- An employment contract or a letter from your employer
- SA302 tax returns and accountant references if you’re self-employed
What happens if your income changes before completion?
Lenders may reassess your application if your income changes before your mortgage completes.
This could include:
- Changing jobs
- Reduced overtime or bonuses
- Going onto maternity leave or sick leave
- Reduced working hours
A change does not necessarily mean your mortgage can no longer proceed, but it may mean affordability needs to be reassessed or a different lender considered. It’s important to tell your mortgage adviser about any changes as early as possible so the correct lender can be selected.
How Kerr & Watson can help
Every lender views income slightly differently. Some might be happy to include bonuses or overtime, while others are stricter.
This is where working with a specialist can make a big difference. We review your payslips, your earnings, and your wider financial picture to match you with lenders who will view your income favourably.
Our team also considers how your protection needs fit into your mortgage plans, offering tailored insurance options to support your financial wellbeing.
Frequently asked questions about payslips and mortgages
Can overtime and bonuses be included?
Yes — many lenders will include overtime, bonuses, and commission, although they usually average this income over several months.
Can I get a mortgage if I’ve just started a new job?
Yes — some lenders will consider applicants in a new role or probation period.
Do lenders contact your employer?
Some lenders may request an employer reference, although this is not always required.
Do mortgage lenders accept online payslips?
Yes, lenders can usually accept electronic payslips, provided they contain the information required and can be clearly read. Requirements vary, so you may be asked to provide the original PDF rather than a cropped screenshot.
Conclusion
The number of payslips you need for a mortgage depends on the lender, how frequently you are paid and the type of income you want the lender to use.
Straightforward basic salary can require relatively little evidence, while overtime, bonuses, commission, recent job changes or other variable income may require additional documents.
Because lenders assess income differently, finding the right lender can make a significant difference when your earnings are not simply a fixed basic salary.
Need help understanding how lenders will assess your income?
At Kerr & Watson, we help clients structure applications correctly and match them with lenders suited to their employment and income situation.
Speak to us today today to secure the right mortgage based on your income and employment situation.











